


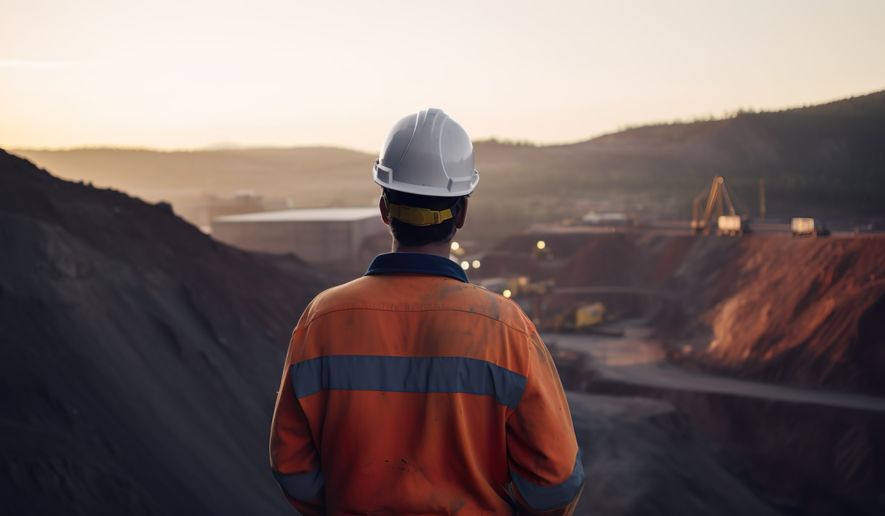
The copper running through your walls, your air conditioner and the power lines on your street hit record prices earlier this year. Prices can move in seconds. A new copper mine takes an average of about 17 years to go from discovery to production.
Is the world running out of copper? Not yet. The International Copper Study Group expects refined copper supply to slightly exceed demand through 2027. But reports from the International Energy Agency, S&P Global and the U.S. Geological Survey point to a tighter long-term picture: demand is projected to keep climbing, the pipeline of new mines is falling behind, and the U.S. is leaning harder on imports. Because buildings and electrical equipment are the largest U.S. uses of copper, that gap matters well beyond electric vehicles.
The International Energy Agency reported that aluminum, copper and tin prices climbed about a third from January 2025 to April 2026. The larger concern lies beyond the current trading cycle. Looking at projects now in the pipeline, the IEA expects copper supply to fall about 25% short in 2035. That is an improvement from the roughly 30% shortfall in its previous outlook, thanks mainly to new projects in the Democratic Republic of Congo and Zambia.
People were interested in these podcasts
Is there a copper shortage right now?
No. Forecasters expect a small refined-copper surplus through 2027, even as the long-term mine pipeline falls short.
The International Copper Study Group forecast Oct. 14 that the global refined-copper market would post a surplus of about 104,000 metric tons, about 115,000 U.S. tons, in 2026, widening to 368,000 metric tons in 2027.
The near-term surplus and the possible 2035 shortage measure different things. The copper study group tracks the near-term balance of refined metal. The IEA assesses whether the mining pipeline can meet expected long-term consumption.
In April, the copper study group cut its demand-growth forecast and raised its estimate of refined production from scrap. Those revisions turned the 150,000-metric-ton deficit it had forecast for 2026 into a small surplus. The group also said limited supplies of mined copper concentrate were holding back refined output. In October, it trimmed its 2026 mine-production growth forecast again, to 1.3%.
Processing costs are rising as well. China restricted sulfuric acid exports in May 2026 after sulfur supplies were disrupted, the IEA said. Copper processing depends on the acid, and the price spike that followed raised production costs for several minerals.
The IEA’s projected 25% gap is not a prediction that one-quarter of demand will go unmet. Higher prices, weaker demand, additional mining projects, recycling and more efficient designs could all narrow it. Substitution offers less relief: S&P Global found that most practical substitutes for copper are already in use. The IEA estimate shows what the currently announced project pipeline can provide under the agency’s assumptions.
What is driving copper demand?
Buildings, the power grid, data centers and defense, not only electric vehicles.
Copper’s largest U.S. market is construction. According to Copper Development Association figures published by the U.S. Geological Survey, the main U.S. uses of copper and copper-alloy products are:
- building construction, 42%
- electrical and electronic products, 23%
- transportation equipment, 18%
Copper is used in wiring, motors, transformers, generators and distribution equipment. The IEA estimated that it makes up roughly 10% to 15% of what transformers and power cables cost. Grid expansion therefore increases demand whether new electricity serves homes, factories, air conditioners, vehicles or data centers.
A January 2026 S&P Global study projected that worldwide copper demand would rise 50%, from 28 million metric tons in 2025 to 42 million in 2040. It attributed the increase to four drivers:
- core economic growth
- the energy transition, including renewables, electric vehicles and grid expansion
- artificial-intelligence infrastructure and data centers
- defense modernization
S&P estimated that data-center demand alone could rise from 1.1 million metric tons in 2025 to 2.5 million in 2040. Its scenarios put that 2040 figure anywhere from 1.7 million to 2.7 million metric tons, depending on power availability and how fast AI is adopted. Even the low end shows why slower electric-vehicle growth would not necessarily ease pressure on supplies.
How long does it take to open a new copper mine?
About 17 years on average from discovery to first production, according to S&P Global, and the timeline has been getting longer.
S&P found much of that time is consumed by permits, environmental reviews and consultations with communities. An earlier IEA review of major mines across several minerals found a similar pattern. Mines that opened from 2010 through 2019 averaged more than 16 years from discovery to first output. Exploration and feasibility work took over 12 years, and construction took four to five.
The wait is growing for mining in general. S&P’s July 2026 study of metal mines of all types averaged 16 years across 232 mines discovered and developed from 1990 through 2025. For 29 projects that have gone through feasibility studies but are not yet producing, the expected wait is nearly 30 years. That is five times the norm of the 1990s, largely because of permitting delays. The United States is slower than average: an April 2025 edition of the study put the average U.S. lead time at 19.1 years, compared with 15.5 years globally.
Permitting is not the only source of delay. Developers must also:
- identify and drill deposits
- determine whether they are economically recoverable
- arrange financing
- design processing facilities
- address water, waste, infrastructure and community concerns
The geology is also getting more expensive. S&P cites falling ore grades and deeper, more remote deposits that raise costs, and its annual review of discoveries shows major new finds remain scarce. Lower-grade ore requires companies to move and process more rock for every pound of copper produced.
How much copper does the U.S. import, and can recycling close the gap?
Net imports covered an estimated 57% of U.S. copper use in 2025, and recycling helps but cannot close the gap on its own.
U.S. mines produced an estimated 1 million metric tons of recoverable copper in 2025, down 5% from 2024, according to the U.S. Geological Survey. The agency said shutdowns of ore-processing plants and declining ore quality at several mines weighed on output. Arizona supplied about 70% of domestic production. The federal government added copper to its official list of critical minerals in November 2025.
Net import reliance increased from 45% of apparent consumption in 2024 to an estimated 57% in 2025. Refined-copper imports reached an estimated 1.7 million metric tons, or about 1.9 million U.S. tons, up from 903,000 metric tons in 2024.
Copper recovered from scrap, including manufacturing scrap, supplied about 30% of U.S. copper supply in 2025, the Geological Survey reported. That has not prevented import dependence from increasing.
Copper can be recovered when buildings are demolished, cables are replaced and vehicles are scrapped, and higher prices give businesses more incentive to collect it. But recycling cannot supply metal before products reach the end of their useful lives, and copper wiring and plumbing can stay in buildings for decades.
The IEA expects copper scrap volumes to surge from around 2030. In its recycling report, the agency projected that with strong policy action, secondary copper’s share of demand could rise from 17% to nearly 40% by 2050. That figure excludes scrap used directly by manufacturers. Reaching it depends on collecting more scrap and building more capacity to process it, the IEA said. S&P is more cautious, estimating that recycling could meet up to a quarter of total demand by 2040 and cannot close the gap without new mines.
At the 17-year average, a copper deposit discovered in 2026 would not begin production until about 2043. Until then, the copper for new wiring, transformers and power lines will have to come from existing mines, projects already in development, scrap and imports.
This article was constructed with the assistance of artificial intelligence and published by a member of The Washington Times' AI News Desk team. The contents of this report are based solely on The Washington Times' original reporting, wire services, and/or other sources cited within the report. For more information, please read our AI policy or contact Steve Fink, Director of Artificial Intelligence, at sfink@washingtontimes.com
The Washington Times AI Ethics Newsroom Committee can be reached at aispotlight@washingtontimes.com.

Please read our comment policy before commenting.