


OPINION:
The Supreme Court has imposed a high bar for President Trump to remove Federal Reserve governors, preserving their monetary policymaking independence.
Presidents almost always want lower interest rates. That is why Congress, through the Banking Act of 1935, created an independent board of governors.
Yet what Congress giveth, it can taketh away, and Americans increasingly favor populist solutions. Insurgent Democrats, for example, want to pack the court to undo its conservative majority.
People were interested in these podcasts
If the Fed does not competently manage its affairs, bank regulation and monetary policy, it could get swept up.
President Trump has taken aim at cost overruns in the $2.5 billion renovation of the Fed’s headquarters. Although the Fed inspector general’s report found no criminal wrongdoing or administrative misconduct, it uncovered gross inadequacies in the project’s management.
The Fed signed a “construction manager at risk contract” that explicitly required a price ceiling. Yet four years after construction began and 18 months after the Fed board determined that the design was complete, it still had not obtained a “guaranteed maximum price.”
Among the worst overruns were the $694 million spent on mechanical, electrical and plumbing work. Those came in $500 million above estimate, and most contracts were awarded after just one or two bids, not the customary three.
This makes the situation ripe for Mr. Trump to pressure former Fed Chairman Jerome Powell to relinquish his seat on the board. That would leave room for a new governor, such as Fed Governor Stephen Miran, who would vote the way the president likes on interest rate policy — not as objective economic conditions would require.
The Fed’s other mandate, bank regulation, has been conducted in a similarly slipshod manner.
Silicon Valley Bank collapsed in 2023 as the Fed raised interest rates. It took large unrealized losses on long-dated Treasurys. Those would have disappeared if the securities had been held to maturity, but depositors panicked, and a run on the bank caused it to close its doors.
The investigation of Michael Barr, who was vice chair for bank supervision, put most of the blame on the bank’s executives. A second investigation, at the behest of the new vice chair, more accurately places the blame on poor regulatory oversight.
The latter shines a harsh light on the Fed’s capacity, as an independent body, to police itself. Mr. Barr remains a governor and is now another likely target of the president’s pressure to resign.
Since 2021, five Fed district bank presidents or governors have faced scandals regarding their personal investing activities. Most recently, fintech lender Enova International announced a definitive agreement to acquire Grasshopper Bank, with the transaction moving forward toward completion.
That combination will benefit consumers by expanding the range of borrowing choices for those with low credit ratings. Mob rule from the left should not dictate federal bank chartering and merger policies.
As George Mason University law professor Todd Zywicki concluded, this is a serious warning to Mr. Warsh and the comptroller of the currency, Jonathan Gould, to clarify federal regulatory standards for reviewing mergers to account for innovative fintech service providers.
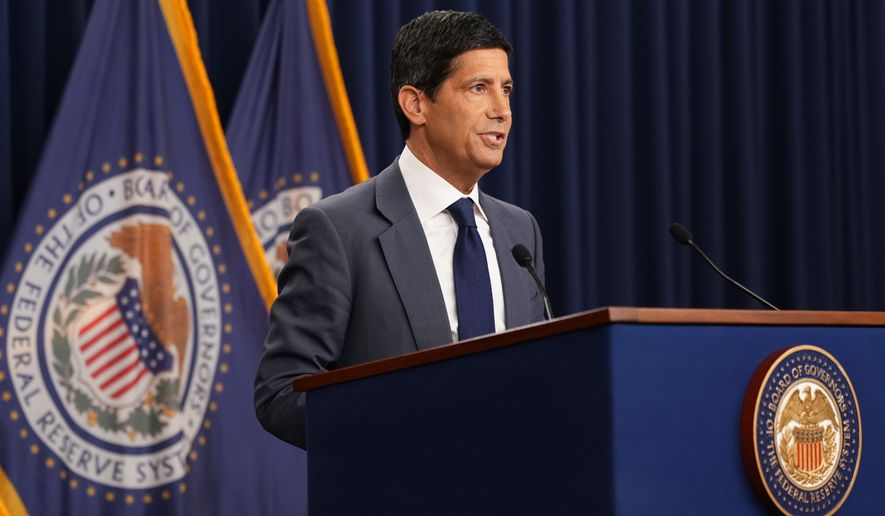
Mr. Warsh has done well to strike five independent task forces to examine how the institution does business, but none of them had a remit for internal management and bank regulation.
To his credit, Mr. Warsh wants a long look at the data and policy frameworks that the Fed uses to combat inflation.
For good reason, the Fed places considerable weight on business and household inflation expectations. Businesses set prices in part based on how much they believe competitors will adjust theirs. Consumers make purchasing decisions and workers adopt postures in wage negotiations based on similar sentiments about future inflation.
Lenders and bond purchasers similarly adjust the interest rates they demand to achieve real returns on their money. There, unlike with apple prices, we cannot observe expectations directly.
Analysts take several broad approaches, including surveys — asking people how much consumer price inflation they expect — and econometric models that process household and business behavior.
These can include observations in bond markets, including the spreads between Treasury Inflation-Protected Securities and ordinary Treasurys. Economists prefer the latter because they provide direct observations of investors’ sentiments.
The Fed tries to combine all of these approaches into a complex Index of Common Inflation Expectations.
In the wake of accelerating inflation driven by COVID-19 overspending and the like, the Fed has repeatedly been wrong about inflation. Its Index of Common Inflation Expectations has remained below 2.35%, averaging 2.22%.
Surveys that simply ask consumers where they think prices are headed, such as those conducted by the University of Michigan, have much more accurately anticipated inflation.
We can only wonder why Mr. Warsh has not taken away his economists’ computers.
• Peter Morici is an economist and emeritus business professor at the University of Maryland, and a national columnist.
Follow the author

Please read our comment policy before commenting.